MFI
  • HOME
  • About
    • About MFI
    • Testimonials
  • Services
    • Accounting and Banking
    • Financial Planning
    • Medical Practice Management
  • Contact
  • Careers
  • Latest News
  • Search
  • Menu Menu
  • Facebook
  • LinkedIn

SARS Scams and eFiling Profile Hijacking: Taxpayers Beware

Tax

“All role players must play their part to prevent criminals from accessing taxpayers’ information.” (SARS)

Every day, too many taxpayers fall victim to convincing scams that use SARS’ name to steal personal information and money.

Cybersecurity Awareness Month (every October) raises awareness about digital security, empowering South Africans to protect their personal data from digital forms of crime. It’s a good time to revisit the growing threat of SARS scams and eFiling profile hijackings.

Common SARS scam types

  • Phishing emails: Members of the public randomly receive false ‘spoofed’ emails, made to look as if they were sent from SARS, but which are fraudulent. Examples include emails appearing to be from returns@sars.co.za or refunds@sars.co.za, indicating that taxpayers are eligible to receive tax refunds. These emails contain links to false forms and fake websites designed to look like SARS sites, with the aim of fooling taxpayers into entering personal information such as bank account details, which criminals then extract and use fraudulently.
  • Fake SMS messages: SARS does not send *.htm or *.html attachments. Any SMS claiming to be from SARS with such attachments is fraudulent.
  • Fake WhatsApp messages: SARS will not provide links to be opened or SARS bank account details for payments on a WhatsApp message.
  • eFiling profile hijacking: Criminals gain access to taxpayers’ eFiling profiles, change banking details, and divert refunds. 

What SARS will and won’t do

SARS will:
✔ Verify your personal details for telephonic engagement and authentication purposes
✔ Communicate through official SARS channels only
✔ Direct you to check your SARS profile on eFiling or the SARS MobiApp for legitimate debts
 
SARS won’t:
✘ Request passwords, one-time pins (OTPs), banking PINs or eFiling login credentials through email, SMS, social media or telephone
✘ Request your banking details in any communication via post, email or SMS (but SARS will verify your personal details for telephonic authentication)
✘ Send hyperlinks to other websites, even those of banks
✘ Ask for your credit card details
✘ Send *.htm or *.html attachments
✘ Provide a SARS bank account number for payments
✘ Ask you to click any link to access its website or services
 

What to do if you suspect a scam 

Do not respond to communications that you suspect to be a scam. Simply contact us and let us provide certainty.

We will check whether the message is part of an official SARS communication campaign or if it’s a known scam message currently in circulation. If it’s a new scam, we can report it to the right authorities.

Before you share personal information or make any payments, we can verify the communication through official SARS channels. For example, if the communication pertains to outstanding debt, we can verify this directly on SARS platforms, as any legitimate debt will reflect on your SARS profile.

How to stay safe beyond Cybersecurity Month 

  • Do not open or respond to emails from unknown sources
  • Be suspicious if a message asks for personal information or creates urgency
  • Never share confidential details with unauthorised individuals
  • Never click on any link to access SARS’ website or SARS services or to verify an account
  • Only use secure internet platforms to access electronic services such as eFiling
  • Enable two-factor authentication on eFiling profiles
  • Use strong, unique passwords and change these regularly

SARS scams are becoming more sophisticated, but the rules for spotting them remain unchanged. When in doubt, and before taking any action, contact us.

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews
September 28, 2026
http://www.mfi.co.za/wp-content/uploads/2026/09/SARS-Scam_650.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-09-28 10:38:432026-09-28 12:23:31SARS Scams and eFiling Profile Hijacking: Taxpayers Beware

Can Business Entertainment Expenses Be Claimed Against Tax?

Tax

“To be deductible the expenditure must be: actually incurred, in the production of income, expended for the purposes of trade, and not of a capital nature.” (SARS)

Business entertainment expenses occupy a unique space in South African tax law. While they may or may not be deductible for income tax purposes under strict rules, a deduction of input VAT on these expenses is generally not allowed.

Income tax deduction? What the law says…

Under Section 11(a) of the Income Tax Act, an expense must satisfy four conditions to be deductible. It must be:

  1. actually incurred
  2. in the production of income
  3. expended for the purposes of trade; and
  4. not of a capital nature

As Judge Watermeyer explained in the landmark Port Elizabeth Electric Tramway Co v CIR case, expenses are deductible when they are “so closely linked to such acts as to be regarded as part of the cost of performing them.” In other words, you must be able to show that the entertainment was genuinely incurred for an income-producing business purpose and was sufficiently closely connected with your trade.

The “production of income” test is the key battleground in entertainment expense disputes. Expenses such as meals, venue hire, and live entertainment may be deductible if the event has a genuine business purpose, for example, entertaining clients or suppliers.

The purpose of the entertainment must be demonstrably commercial. You are required to retain sufficient records to demonstrate compliance with tax law. This might be in the form of a documented agenda or meeting notes, or a comprehensive function schedule including the date, venue, attendees, and the specific business objective. 

VAT? Almost never…

Even if an entertainment expense qualifies for an income tax deduction, you generally cannot deduct input VAT on entertainment such as client meals, beverages, or hospitality. That’s because Section 17(2)(a) of the VAT Act explicitly prohibits input tax deductions on entertainment.

Entertainment is broadly defined in the VAT Act as “the provision of any food, beverages, accommodation, entertainment, amusement, recreation or hospitality of any kind.” This covers:

  • staff refreshments (tea, coffee, snacks)
  • business lunches and dinners
  • catering for staff canteens
  • annual functions (venue hire, entertainment, staff costs)
  • marketing promotions and events
  • entertaining clients at restaurants, bars and nightclubs

The exceptions

There are nine express exceptions to the prohibition on input VAT recovery for business entertainment expenses, of which two are especially important.

  1. Where the vendor is in the business of supplying entertainment (to either customers or employees), the vendor may generally claim VAT on inputs used to make its taxable supplies, provided the statutory requirements are met. SARS explains that the entertainment must generally be supplied for consideration intended to cover the direct and indirect costs, or meet the relevant open-market-value rules.  
  2. Input VAT may generally be claimed on an employee’s qualifying meals and accommodation where the employee is required by their duties to spend at least one night away from both their usual residence and usual workplace, and the trip relates to making taxable supplies on behalf of the vendor.

Ducks in a row

The Tax Administration Act places the burden of proof on the taxpayer. To satisfy SARS during an audit, you must maintain contemporaneous records for every entertainment claim and retain these for at least five years from the submission date of the return in which the expense was claimed.  It’s a good idea to include the following:

  1. Date and location of the event
  2. Full names and company details of clients and staff present
  3. A specific description of the business purpose or commercial discussion
  4. Itemised tax invoices and proof of payment

Mind the audit

Professional advice is strongly recommended before claiming entertainment expenses, because a claim for entertainment expenses is likely to be flagged for investigation by SARS.

Our expert oversight before claiming will ensure your tax position is verified, that you have adequate proof that the claims are for legitimate business expenses, and that the cost, time and risk of a SARS audit are justified by the tax savings claimed.

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews
September 28, 2026
http://www.mfi.co.za/wp-content/uploads/2026/09/Business-entertainment_650.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-09-28 09:58:382026-09-28 12:42:47Can Business Entertainment Expenses Be Claimed Against Tax?

Cut Your Tax Bill: Rebates and Incentives Available This Tax Season

Tax

“Next to being shot at and missed, nothing is quite as satisfying as an income tax refund.” (F.J. Raymond)

SARS offers a range of rebates, incentives and deductions that can significantly reduce the tax you need to pay, if you know where to look. The challenge is knowing which ones will apply to your situation this Tax Filing Season 2026 (covering the period between 1 March 2025 and 28 February 2026) and how to claim them correctly.

We’ve put together handy (but by no means exhaustive) lists for individuals and businesses.

For individuals

Thanks to rebates available to taxpayers, you only start paying tax when you earn more than a certain amount. For the 2026 Tax Season, that amount is R95,750 if you are under age 65 (increased to R99,000 for the 2027 tax year). The thresholds are much higher for those aged between 65 and 75 and those older than 75. These are automatic rebates that reduce the tax you pay before any other relief is applied.

Medical scheme contribution tax credits provide a monthly rebate for the main member and first dependent, plus lower amounts per month for each additional dependent. If your medical expenses exceed a certain threshold, you may also qualify for additional medical tax credits based on your total out-of-pocket medical costs for the year.  

Interest from a South African source up to R23,800 per annum is exempt from income tax when earned by any natural person under 65 years of age (R34,500 over 65) or a deceased estate.

Retirement fund contributions to a registered pension, provident or retirement annuity fund are deductible up to 27.5% of the greater of your taxable income or remuneration, calculated as per the income tax rules, capped at R350,000 per year (increased to R430,000 for the 2027 tax year). This is one of the most powerful ways to lower your tax bill while building long-term savings.

Tax-free savings accounts remain one of the simplest ways to build wealth tax-efficiently. All returns, including interest, dividends and capital gains, are 100% tax free. The annual contribution limit for the 2026 tax year was R36,000 (increased to R46,000 for the 2027 tax year), and the lifetime limit is R500,000.

If you work from home and have a dedicated home-office area used for your trade, you may be able to deduct a portion of your rent, utilities, rates and wear-and-tear on office furniture or equipment on a pro-rata basis. The rules are specific, and there are potential downsides to claiming, so professional guidance is recommended.

Donations to section 18A-approved organisations are deductible up to 10% of taxable income calculated in accordance with legislation. Any excess is carried forward to the following tax year.

For businesses

Small Business Corporations (SBCs) benefit from tax relief including immediate write-off of qualifying new plant or machinery, significantly reducing taxable income in years when you invest in equipment, as well as a wear-and-tear or accelerated allowance on other depreciable assets and a progressive tax rate that can deliver substantial savings for qualifying smaller businesses.

Micro businesses (turnover of R1 million or less, upped to R2.3 million for 2027) may qualify for a simplified turnover tax, instead of the usual taxes payable by companies, such as income tax, provisional tax and Capital Gains Tax (CGT).

There are also specific accelerated depreciation allowances for manufacturing and other assets used in the production of renewable energy.

Employers who register SETA learnership agreements qualify for additional tax deductions beyond the actual training cost, reducing taxable income while building skills.
Qualifying research and development costs are 150% deductible, with accelerated depreciation on R&D machinery and capital assets.

Other deductions worth noting include the Urban Development Zone allowance, the Special Economic Zones incentive offering a reduced corporate tax rate of 15%, and a potential accelerated building allowance for new and unused buildings and improvements to a building at 10% of cost per year. Business owners aged 55 or older might also qualify for a capital gains exemption when selling a business. 

Do you qualify?

These are just some of the rebates, deductions and incentives available for the 2026 Tax Season. The difference between a good tax outcome and a great one often comes down to knowing which relief measures apply and how to claim them correctly. Our team stays on top of every change, so you don’t have to.

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews
August 27, 2026
http://www.mfi.co.za/wp-content/uploads/2026/08/Rebates-650x300-1.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-08-27 14:07:052026-09-01 10:04:58Cut Your Tax Bill: Rebates and Incentives Available This Tax Season

SARS Moves Traveller Declarations Online

Tax

“In my travels across the globe, I’ve come to believe that Franz Kafka wasn’t writing fiction but rather a traveller’s guidebook.” (Ned Donovan)

South Africans and foreigners crossing our border (on arrival and departure) are now required to complete one more step before they travel: an online declaration to SARS covering goods, cash and other items in their possession. The system, which is already in place across South Africa’s air, land and sea borders, became compulsory from 1 July 2026 and is part of a broader push to digitise customs controls and tighten oversight at the border.

A flurry of conspiracies

Since the announcement, social media has been flooded with conspiracy theory videos alleging ulterior motives. But the documentation released by SARS reveals travellers need not fear: this new requirement is not an income-tax filing in disguise. The available guidance makes clear that it is a customs measure aimed at simply improving how travellers declare goods, currency and other regulated items when entering or leaving the country.

So, what’s really going on?

SARS says the online process replaces much of the old manual declaration system and is intended to make compliance easier, create a smoother traveller experience and strengthen risk management at ports of entry. In practice, that means customs officials receive information earlier and can respond before a traveller reaches the inspection point.

The system asks travellers to submit their details before travel, including passport information, travel plans, contact details and the names of companions. Adults must also complete declarations for children or infants travelling with them. Once the form is submitted, the traveller receives an electronic confirmation by email. That confirmation must be kept on a mobile phone or printed out, and it contains instructions on what to do at the port of entry or departure. Travellers arriving in South Africa are directed through customs according to those instructions, while departing passengers may be told whether they need to report to customs before leaving.

When will it impact you?

For businesspeople and frequent travellers, the commercial significance lies in what must be declared. Ordinary personal belongings such as clothing, a phone or a laptop for personal use do not need to be listed. But goods above duty-free thresholds, items intended for resale or business use, and cash above the legal limits do. The guidance provided in the source material states that goods with a value up to R5 000 per person are duty-free, while goods above that level may trigger duty and VAT, with normal customs duty and VAT applying above R25 000. Cash above R100 000 must also be declared.

The rules haven’t changed, the method of declaration has. A traveller returning with expensive goods, a businessperson carrying samples, or an entrepreneur moving stock across the border may all face duties, VAT or reporting obligations depending on what they are carrying. The online declaration gives SARS a digital record in advance and gives travellers a clearer process to follow.

Tried and tested

SARS says the system was first piloted at OR Tambo, Cape Town International and King Shaka airports in 2022 before being expanded nationally. The message to travellers is straightforward: border declarations have moved online, and failing to declare goods or giving false information could lead to delays, penalties or the seizure of goods. For anyone crossing South Africa’s borders, customs compliance is now a digital-first process.

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews

August 27, 2026
http://www.mfi.co.za/wp-content/uploads/2026/08/Traveller-declaration-650x300-1.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-08-27 14:01:292026-08-27 14:01:29SARS Moves Traveller Declarations Online

Provisional Tax Time: First Payment for 2027 Tax Year Due 31 Aug

Tax

“Provisional tax is merely an advance payment of a taxpayer’s normal tax liability.” (SARS)

For many taxpayers, it feels as if you’re making income tax payments all the time.

It’s not far from the truth because, in South Africa, provisional taxpayers make two compulsory payments (and possibly a third voluntary payment) each year. And that’s even before the annual income tax deadline in January of the following year, when any further tax liability will become due. 

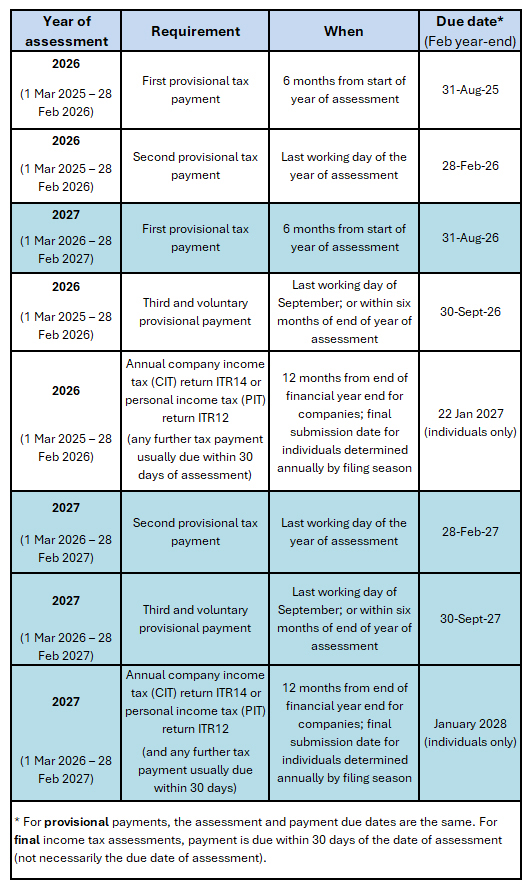
As a result, there are numerous deadlines that overlap across tax years. Yes: it is confusing, as the table below illustrates. But there’s no point throwing your arms up in the air: provisional tax non-compliance is met with some of the harshest penalties imposed by SARS.

Provisional and income tax timelines

Who are ‘provisional taxpayers’?

  • All companies except those specifically excluded
  • Any person who earns income which is not remuneration, an allowance or advance or who earns remuneration from an employer not registered for employees’ tax except those specifically excluded
  • A labour broker with an exemption certificate
  • Any person notified by the Commissioner of SARS

Why must provisional tax be paid?

Provisional tax payments are like instalments on taxpayers’ annual income tax, paid in advance and spread over two or three payments during the year. These payments are deducted against any tax owing after the year’s final income tax return is filed – at which point any further tax liability will then become due.

The objective is to prevent taxpayers from facing large income tax liabilities that are only revealed at the end of the year of assessment. 

How is provisional tax declared and paid?

  • Provisional tax payments are calculated on estimated taxable income, including current taxable capital gains, for that particular year of assessment.
  • The estimates, says SARS, must be determined sensibly and by careful reasoning and judgment, in a mathematical manner, and using experience, common sense and all available information.
  • The first period estimate is forward-looking, requiring companies to estimate their taxable income for the year ahead and then to pay tax on this estimate in advance.
  • In contrast, the second period provisional return is retrospective, since by the year-end there is more certainty regarding the income for the year, and the tax due thereon.
  • These estimates of taxable income are submitted to SARS on an IRP6 return, which must be submitted by all provisional taxpayers for the first and second periods.
  • Even if you or your company owes no tax, a ‘nil’ return showing taxable income is equal to zero must still be filed on time.
  • If an IRP6 is filed more than four months after the deadline, SARS considers a ‘nil’ return to have been submitted, and unless the actual taxable income is really zero, this will result in penalties.
  • Accurate records of all the calculations and source documents used must be kept as SARS can ask for the estimate to be justified and, if dissatisfied with the amount, increase the estimate.

Do call on our professional assistance

All taxpayers are ultimately responsible for their tax affairs, even though provisional tax is particularly daunting and confusing, with so many overlapping deadlines, complex requirements and harsh penalties.

Expert tax advice is highly recommended to ensure compliance with the requirements and the filing and payment deadlines. You know who to call.

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews

July 29, 2026
http://www.mfi.co.za/wp-content/uploads/2026/07/Provisional-Tax_650x300.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-07-29 09:28:132026-07-29 13:07:21Provisional Tax Time: First Payment for 2027 Tax Year Due 31 Aug

2026 Tax Season Opens: Experience the Power of Done

Tax

“The Power of Done starts with knowing when to act.” (SARS)

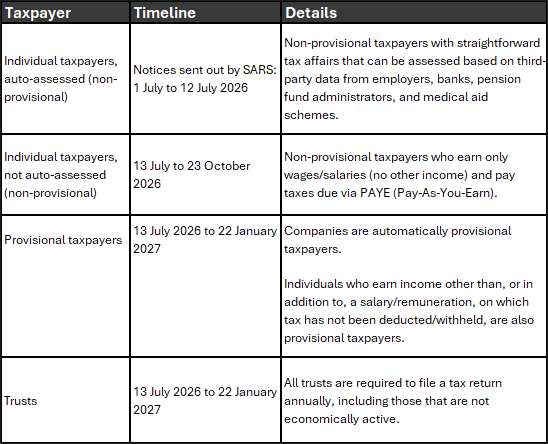
The 2026 Tax Season officially opens on 13 July 2026 for the 2025/2026 year of assessment, covering the period between 1 March 2025 and 28 February 2026.

During filing season, taxpayers must complete and submit their tax returns, declaring their income and deductions to allow SARS to determine their final tax liability for the period under assessment.

Dates to diarise
What’s new this filing season
  • “The Power of Done”: This year SARS is inviting taxpayers to experience “The Power of Done”, a campaign that centres on Auto-Assessments. SARS says that if you agree with your auto-assessment, you don’t need to manually file a return or do anything else, truly experiencing “The Power of Done”.
  • More prefilled data: More taxpayer information from third parties like employers, banks, medical schemes, insurers and retirement funds, is already pre-populated on returns, which means less time spent on capturing data and hopefully fewer mistakes.
  • Stricter verification: SARS has upgraded its data-matching algorithms. So even if auto-assessed, make sure to double-check that all your data (like deductions and donations) is accurate.
  • WhatsApp integration: Taxpayers can now receive their Notice of Assessment (ITA34) or Statement of Account (SOA), as well as securely upload supporting documents, directly via WhatsApp.
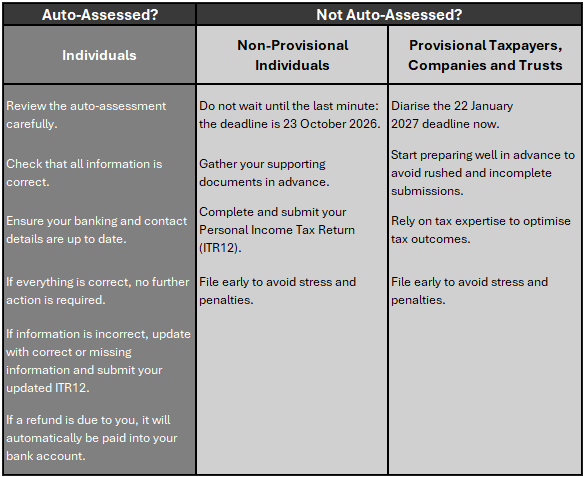
To be or not to be auto-assessed… Here’s what to do
Rely on our expertise for a hassle-free filing season 

This is what we can do for you:

  • Verify all SARS communications are legitimate to protect you from scams.
  • Check that all taxpayer and banking details are correct and updated with SARS to facilitate refunds and to prevent identity theft and fraud.
  • Claim every tax rebate available to you to avoid you paying more tax than required.
  • Correctly prepare all required documentation early to avoid last-minute delays and to expedite a possible SARS verification or audit.
  • Check auto-assessments to ensure these are correct before they are accepted.
  • Ensure that your tax return submissions comply with current regulations.
  • Meet all submission deadlines on your behalf to avoid penalties.

Our team of seasoned tax professionals is ready to make this filing season a doddle!

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews

June 26, 2026
http://www.mfi.co.za/wp-content/uploads/2026/06/2026-tax-season_650x300.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-06-26 10:26:492026-06-26 10:26:492026 Tax Season Opens: Experience the Power of Done

Non-Compliant Trust? Penalties are Piling up…

Tax, Trusts

“Trustees are reminded that compliance is mandatory, and non-compliance can result in fines and penalties.” (SARS)

SARS has significantly increased its scrutiny of trust administration. What’s more, from the beginning of May 2026, automated administrative penalties apply to all non-compliant trusts – without exception.

Whether a trust is active or dormant, the trustees have a legal obligation to comply with SARS requirements, and the consequences of failing to do so are now immediate and ongoing. 

What does trust compliance entail?

All trusts must:

  • File a tax return (ITR12T) annually, whether economically active or not. 
  • Update and maintain trust information reflected on the SARS system.
  • Maintain a detailed organogram and records of the founder, trustees, donors, and beneficiaries.
  • Maintain strict records of financial statements, trust deeds, and minutes of trustee meetings.
  • Submit IT3(t) returns reporting detailed information on distributions and amounts vested in beneficiaries, enabling SARS to cross-reference data with beneficiaries’ personal tax returns. 
  • Some trusts may also be subject to provisional tax requirements.
Who is responsible?

Trustees act as representative taxpayers of a trust in terms of the Income Tax Act and personally bear sole responsibility for ensuring full compliance.

This includes maintaining accurate trust information, ensuring that all legal and tax obligations are met, and initiating deregistration processes for trusts that meet the applicable criteria.

Consequences of non-compliance

From 4 May 2026, SARS will issue a penalty assessment notice for all outstanding trust income tax returns for tax periods from 2024 onwards.

Designed to encourage compliance, these penalties are applied consistently, recurring monthly until non-compliance is corrected. Monthly administrative penalties may range from R250 to R16,000 per outstanding return, depending on the trust’s taxable income for the preceding year and will accumulate until the non-compliance is corrected, up to a maximum of 35 months.

It doesn’t stop there. SARS may in specific circumstances hold trustees personally liable for the trust’s tax debts, and trustees are individually and jointly liable for the trust’s tax compliance.

In addition, non-compliance with SARS obligations may be regarded as a criminal offence and will attract penalties and interest. Trustees who fail to act face penalties, interest, and potential criminal charges.

What if my trust is no longer in use? 

SARS requires all registered resident trusts, without exception (and certain qualifying non-resident trusts), to meet the range of ongoing obligations.

A trust’s tax compliance obligations only come to an end once it has been formally deregistered with SARS. Until this process is finalised, the trust remains active for tax purposes and is exposed to penalties for continued non-compliance.

Where a trust is no longer being used for its intended purpose, trustees are encouraged to formally terminate the trust. The first step is to regularise the trust’s tax affairs by submitting all outstanding returns, settling all tax liabilities, and updating all trust information.

Thereafter the trust can be formally terminated through the Office of the Master of the High Court. Once the Master has issued written confirmation of termination, trustees can ask SARS to deregister the trust for income tax purposes.

Count on our expertise

If you have a trust, active or not, and are uncertain about its compliance status, contact us for expert advice and professional assistance.

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews

May 27, 2026
http://www.mfi.co.za/wp-content/uploads/2026/05/tax-compliant_650x300.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-05-27 12:48:002026-05-27 12:48:00Non-Compliant Trust? Penalties are Piling up…

Selling Your Business to Retire? Get This Tax Relief!

Business, Tax

“A small business is an amazing way to serve and leave an impact on the world you live in.” (Nicole Snow)

Small business owners looking to sell their business or interest in a business as part of their retirement planning will be glad to know that meaningful tax relief has been provided for them in the 2026 National Budget.

Among other measures to support businesses, National Treasury raised the capital gains tax exemption for the sale of a small business for older persons (55+) from R1.8 million to R2.7 million, a long-overdue adjustment for inflation and rising asset values.

The higher exemption also applies to more businesses than it did before. Where small businesses used to be defined as those valued at R10 million or less, the limit has been increased to R15 million.

Do I qualify?

First check if you meet the bare minimum requirements:

  • The exemption applies to individuals aged 55 or older.
  • The exemption applies when disposing of a small business with a market value not exceeding R15 million.
  • The market value of all assets, regardless of their nature, must be considered in determining whether the R15 million threshold is exceeded or not.
  • Liabilities of the business are ignored for this determination.
  • For partnerships or companies, the R15 million threshold applies to the total assets of the business, not each partner or shareholder’s fractional interest. This means a two-partner business with R20 million in assets will not qualify, even if each partner’s share is only R10 million.
  • The lifetime CGT exemption is capped at R2.7 million in total across all disposals.
  • Each asset must have been held continuously for at least 5 years prior to disposal and the individual that qualifies for the relief had been substantially involved in the operations of the business of that small business during this period.
  • The relief must be determined on an asset-by-asset basis.

Given the complexity of this determination and SARS’ requirement that relief must be determined on an asset-by-asset basis, professional tax assistance is highly recommended.

How could it benefit you?

Many small business owners rely on the eventual sale of their business as their primary retirement asset.

This tax relief can support succession planning, intergenerational transfers, and smart business exits, particularly for family-owned businesses. It encourages the sale of businesses, effectively unlocking capital and allowing for business continuity or reinvestment into the economy. 

Of course, the additional tax-free capital gain will also meaningfully boost your retirement security after years of building a business.

If you’re considering retiring or selling soon, it’s worth reviewing your timing with a tax advisor. We can assist you in reviewing your business valuation, assessing your CGT exposure and structure and timing your exit correctly to make the most of this meaningful tax exemption.

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews

April 29, 2026
http://www.mfi.co.za/wp-content/uploads/2026/04/sell-business_650x300.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-04-29 07:41:082026-04-29 07:41:08Selling Your Business to Retire? Get This Tax Relief!

Annual Employer Tax Recon Due End May  

Tax

“Only accountants can save the world — through peace, goodwill, and reconciliations.” (Unknown)

Employers are legally required to submit their EMP501 reconciliation with accurate and up-to-date payroll and tax information (including valid Income Tax Reference Numbers) for their employees during the Employer Annual Declaration season that runs from 1 April to end May 2026.

This involves submitting an accurate Employer Reconciliation Declaration (EMP501), issuing Employee Tax Certificates [IRP5/IT3(a)s] and, if applicable, a Tax Certificate Cancellation Declaration (EMP601).

The submission must further balance across the three elements: monthly EMP201 returns for the period, the payments made to SARS, and the employees’ IRP5/IT3(a)s generated. As such, it provides an important opportunity to correct any errors that may have occurred during the year.

Preparing and submitting a correct and complete declaration on time can be technically challenging, especially for larger employers. But you neglect it at your peril, as it is a focus area for SARS and the consequences of non-compliance are many.

SARS focus area

The Annual Employer Reconciliation Declarations is a focus area for SARS, as it not only ensures employer compliance, but also enables SARS to issue individual taxpayers with pre-populated Income Tax Returns (ITR12) and income tax auto-assessments.

For this reason, employers can expect ongoing and increased scrutiny from SARS in this regard.

Technical challenges

Submitting a declaration that is correct, complete and on time (before end May) has always been technically challenging. But it just got even harder, as SARS has now upgraded missing or incorrect mandatory Income Tax Reference Numbers from a warning-level defect into a hard-stop submission defect when completing a declaration.

This means that employee details must be verified before submission and employees without tax numbers must be registered with SARS before the company EMP501 can be submitted. Missing or invalid employee tax numbers result in incomplete submissions that will prevent IRP5 certificates from being captured, causing delays and non‑compliance for the company and all employees.

Because so many employers struggle with technical challenges like these, SARS is rolling out technical clinics this year to make compliance easier. Or you could just let us handle it for you.

Consequences of non-compliance

Submitting incorrect or incomplete details, or submitting after the deadline, can result in:

  • Additional admin, time and cost
  • Employer penalties
  • Delays in obtaining an employer’s tax compliance status
  • Unexpected tax outcomes for employees

In addition, if the EMP501 submitted is audited by SARS and PAYE liability is amended, the employer is required to re-submit the EMP501 as per the audit result.

Expert assistance is at hand

As the deadline looms, employers can be assured of technical challenges, increased SARS scrutiny, and even more tax-related admin and cost. All very good reasons to rely on our tax expertise and experience to ensure you submit correctly and on time.

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews

April 29, 2026
http://www.mfi.co.za/wp-content/uploads/2026/04/EMP501_650x300.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-04-29 07:34:572026-04-30 10:18:31Annual Employer Tax Recon Due End May  

When Growth Is a Tax Problem

Business, Tax

“As your profitability grows, your taxes will too. In fact, paying more taxes is an indicator that your business health is improving.” (Mike Michalowicz)

Business owners work hard to grow revenue and increase profit. What often receives less attention is how that growth alters your tax obligations. Higher turnover can trigger VAT registration. Rising profit increases provisional tax exposure. Hiring staff adds payroll compliance risk. Expansion across borders introduces new tax jurisdictions. Even improved margins can create cash flow pressure when tax payments are due before debtors settle their accounts.

Crossing the VAT threshold

In South Africa, once your taxable supplies exceed the compulsory registration threshold (recently increased from R1 million per year to R2.3 million per year), you must register for VAT. Many businesses grow quickly and miss the moment they cross it. This simple mistake can trigger penalties, interest, and backdated VAT.

Cash flow can become a second issue. You collect VAT on sales, but input VAT claims lag if suppliers don’t issue proper invoices. If you price incorrectly, you may end up funding VAT from your own margin. You might even have to pay output VAT on sales before you have received payment from your debtors.

Growth often means higher transaction volume as well. That increases the risk of errors in VAT coding, zero-rated supplies, and mixed-use expenses. It’s easy to see how a small bookkeeping mistake can easily become a material tax exposure.

Of course, there can also be benefits to registering for VAT, not least the potential right to claim input VAT on certain assets that have been purchased before you registered for VAT, and that are now used to make taxable supplies. VAT must however have been charged at the time of purchase. This can provide a nice inflow of cash, if handled correctly. Bottom line: speak to your accountant!

Provisional tax shocks

When profit rises, so does income tax. Owners often draw more cash as profits rise. They forget that tax on those profits has not yet been paid, and by the time the assessment arrives, the money is gone.

Provisional tax can be particularly problematic. Estimates based on last year’s lower profits lead to underpayment penalties when actual results are filed. Rapid growth can produce a large balancing payment in the second provisional period, or at year end.

Payroll expansion and compliance risk

Hiring staff is a sign of progress. It also triggers pay-as-you-earn (PAYE), unemployment insurance fund (UIF), and skills development levy (SDL) obligations. Errors in payroll setup multiply as your headcount increases. If payroll software isn’t configured correctly, you can under-deduct PAYE. Add penalties and interest, and growth in staff numbers can become a financial setback.

Share incentive schemes and other fringe benefits introduce potential tax complications. Without guidance, these benefits can be structured in ways that create unexpected tax costs for both employer and employee.

Operating across borders

Sometimes growth means selling beyond South Africa’s borders. Cross-border trade brings customs duties, foreign VAT, transfer pricing, and double taxation agreements into play.

A small e-commerce business that starts shipping internationally may create a permanent establishment in another jurisdiction without even realising it. That can expose them to foreign corporate tax. Currency gains and losses add volatility. If not monitored carefully, taxable income can rise even when cash flow does not.

Structural strains

The structure that worked at start-up may not suit a larger business. A sole proprietorship with modest turnover may be efficient. The same structure with higher profit can push you into a steeper marginal tax bracket.

When investors buy into new structures, share issues and valuations may raise capital gains tax and income tax questions if roll-over relief is not available. Growth may also expose structural weaknesses. Dividends tax and loans between shareholders and companies can create further tax considerations.

Capital expenditure and allowances

Expanding operations usually requires additional equipment, vehicles, or property. Tax deductions for capital assets now need to be considered. Meanwhile, disposal of older equipment may trigger recoupments or capital gains taxes. A growing business that upgrades assets frequently should definitely model the tax impact of these upgrades before committing.

Cash flow versus profit

Rapid growth often ties cash up in stock and debtors. Profit on paper doesn’t mean cash in the bank. Tax is calculated on taxable income, not on what clients have paid. What this all means is that a business can show strong profit, and owe tax on that profit, but still struggle to pay tax because of cash flow issues. Cash flow forecasting must include tax forecasting.

Audit risk

As turnover grows, so does visibility. Larger payrolls, higher VAT submissions, and bigger provisional payments attract scrutiny. Inaccurate returns that went unnoticed at a small scale can become costly when the numbers are larger.

Internal controls that were informal at start-up stage now need formal processes. Documentation matters. Contracts, invoices, and board resolutions must support your tax position. Without them, assessments become difficult to dispute.

Planning for growth, not reacting to it

Growth doesn’t create tax problems on its own. Lack of planning does.

Review your tax registrations before revenue spikes, update provisional tax estimates during the year, and align owner withdrawals with after-tax profit, not turnover. It’s also important that you reassess your entity structure as profit bands change, and model the tax impact of hiring, investing, or expanding offshore before you act.

Growth is a good problem to have. But it is still a problem if ignored. Engage your accountant early in the growth phase, not after the assessment arrives.

Disclaimer: The information provided herein should not be used or relied on as professional advice. No liability can be accepted for any errors or omissions nor for any loss or damage arising from reliance upon any information herein. Always contact us for specific and detailed advice.

© AccountingDotNews

March 27, 2026
http://www.mfi.co.za/wp-content/uploads/2026/03/ADN_When-Growth-Is-a-Tax-Problem_650x300.png 300 650 MFI http://www.mfi.co.za/wp-content/uploads/2023/09/cropped-cropped-MFI-Logo-Icon.jpg MFI2026-03-27 10:36:352026-03-27 10:36:35When Growth Is a Tax Problem
Page 1 of 7123›»

Pages

  • About
  • Accounting and Banking
  • Careers
  • Careers-PTA01
  • Contact
  • Financial Planning
  • HOME
  • Latest News
  • Medical Practice Management
  • MFI Team
  • Testimonials

Categories

  • Accounting
  • Business
  • Company / Corporate / Compliance
  • DotNews
  • Economy
  • Employment and Labour
  • Employment and Labour Law
  • Financial
  • Investment
  • Tax
  • Technology
  • Trusts
  • Uncategorized
  • Wills and Estate Planning

Archive

  • September 2026
  • August 2026
  • July 2026
  • June 2026
  • May 2026
  • April 2026
  • March 2026
  • January 2026
  • November 2025
  • October 2025
  • September 2025
  • August 2025
  • July 2025
  • June 2025
  • May 2025
  • April 2025
  • March 2025
  • February 2025
  • January 2025
  • July 2023
  • June 2023
  • May 2023
  • April 2023
  • March 2023
Standard POPI Act Privacy Policy Statement

Scroll to top